Skip to content

Elgar History

Know The Ancient Times.
  • Home
  • Blog
  • Archaeology
  • History Museums
  • Contact
  • Privacy Policy
Trending Now
April 1, 2020 The top 10 most popular history topics
9 Interesting Historical Events That Are Lesser-Known
Categories Blog

9 Interesting Historical Events That Are Lesser-Known

  • 7 years ago
30 Great History Research Paper Topics
Categories Blog

30 Great History Research Paper Topics

  • 7 years ago
Philosophy of History
Categories Blog

Philosophy of History

  • 7 years ago
The 10 Most Important Moments and Events in History
Categories Blog

The 10 Most Important Moments and Events in History

  • 7 years ago

Popular Post

Geelong’s Nyaal Banyul records 12,200 attendees as local suppliers join the event business
Categories Blog

Geelong’s Nyaal Banyul records 12,200 attendees as local suppliers join the event business

  • By Jeremy Bowen
  • 2 hours ago

Geelong’s new convention centre welcomed more than 12,200 attendees across 15 events in its first month after opening in July.…

Australia Post’s 2026 report shows online spend hit $82.6 billion, and boxes are getting smaller
Categories Blog

Australia Post’s 2026 report shows online spend hit $82.6 billion, and boxes are getting smaller

  • By Jeremy Bowen
  • 2 months ago

Australians spent $82.6 billion online in 2025, a 14% jump year on year, according to Australia Post’s latest eCommerce Report.…

How Manufacturer Certification Fits Austin’s Post-Hail Roofing Backlog
Categories Blog

How Manufacturer Certification Fits Austin’s Post-Hail Roofing Backlog

  • By Jeremy Bowen
  • 2 months ago

Central Texas is accustomed to hail-driven repair surges, and statewide claim data shows why contractor availability can tighten quickly after…

What the 50% Aluminum Tariff Means for Las Vegas Patio Covers Built in the USA
Categories Blog

What the 50% Aluminum Tariff Means for Las Vegas Patio Covers Built in the USA

  • By Jeremy Bowen
  • 3 months ago

Aluminum doesn’t usually make the local news in Las Vegas. It’s the metal holding up half the patios in the…

Long Reads

Geelong’s Nyaal Banyul records 12,200 attendees as local suppliers join the event business
Categories Blog

Geelong’s Nyaal Banyul records 12,200 attendees as local suppliers join the event business

Australia Post’s 2026 report shows online spend hit $82.6 billion, and boxes are getting smaller
Categories Blog

Australia Post’s 2026 report shows online spend hit $82.6 billion, and boxes are getting smaller

How Manufacturer Certification Fits Austin’s Post-Hail Roofing Backlog
Categories Blog

How Manufacturer Certification Fits Austin’s Post-Hail Roofing Backlog

Popular Latest Comments
Geelong’s Nyaal Banyul records 12,200 attendees as local suppliers join the event business
Categories Blog

Geelong’s Nyaal Banyul records 12,200 attendees as local suppliers join the event business

  • By Jeremy Bowen
  • 2 hours ago
Massage Spa Treats Or A Massage Chair – Why They’re A Great Gift Idea
Categories Blog

Massage Spa Treats Or A Massage Chair – Why They’re A Great Gift Idea

  • By Jeremy Bowen
  • 6 years ago
Geelong’s Nyaal Banyul records 12,200 attendees as local suppliers join the event business
Categories Blog

Geelong’s Nyaal Banyul records 12,200 attendees as local suppliers join the event business

  • By Jeremy Bowen
  • 2 hours ago
Australia Post’s 2026 report shows online spend hit $82.6 billion, and boxes are getting smaller
Categories Blog

Australia Post’s 2026 report shows online spend hit $82.6 billion, and boxes are getting smaller

  • By Jeremy Bowen
  • 2 months ago
No comments to show.

Info Insight

Geelong’s Nyaal Banyul records 12,200 attendees as local suppliers join the event business
Categories Blog

Geelong’s Nyaal Banyul records 12,200 attendees as local suppliers join the event business

  • 2 hours ago
Australia Post’s 2026 report shows online spend hit $82.6 billion, and boxes are getting smaller
Categories Blog

Australia Post’s 2026 report shows online spend hit $82.6 billion, and boxes are getting smaller

  • 2 months ago
How Manufacturer Certification Fits Austin’s Post-Hail Roofing Backlog
Categories Blog

How Manufacturer Certification Fits Austin’s Post-Hail Roofing Backlog

  • 2 months ago
What the 50% Aluminum Tariff Means for Las Vegas Patio Covers Built in the USA
Categories Blog

What the 50% Aluminum Tariff Means for Las Vegas Patio Covers Built in the USA

  • 3 months ago
What the Harvard Dental Desert Study Says About Reaching a Specialist in a Town Like Kyle
Categories Blog

What the Harvard Dental Desert Study Says About Reaching a Specialist in a Town Like Kyle

  • 4 months ago

From Our Blog

The Most Amazing Archaeology Findings

March 5, 2020April 4, 2020
Archaeological finding

The Most Amazing Archaeology Findings

Whether, or not, you love archaeology, or the mere idea of digging up the past and more specifically the remains of people who lived hundreds to thousands of years ago freaks you out, then this article is still for you.
Why? Well, the findings and discoveries of people, artefacts and stories are so interesting and some Sci-Fi-worthy, that it’s hard to believe such things even exist.
Luckily most of these findings, don’t even include human remains at all, so even though we might be sharing a little dust with you, luckily none of it was derived from the casket itself.

Amazing Archaeology

The Top Archaeological Discoveries in the World

#1 The Rosetta Stone

Known as one of the most famous artefacts to ever be found, which was discovered in 1799, by a group of French soldiers, who was at the time, busy rebuilding a military fort in Egypt, the Rosetta Stone stirred excitement in many archaeologists’ hearts, to say the least.
This ancient slab was carved all the way back in 196 B.C, and even royal decree, which was issued by priests, for the Ptolemaic Empire in Egypt’s ruler, Ptolemy V.
To many people’s disappointment, it’s not the message itself that accounts for its fame, but how it was written, which is the decree of these priests, inscribed in three scripts, which includes the ancient Egyptian demotic script, the Egyptian hieroglyphs, as well as one in ancient Greek. The Rosetta Stone was placed in the British Museum in 1802.

#2 Troy

Now, of course, you’ve seen the movie, Troy, and yes, the actual site of the entire storyline behind the film exists.
This archaeological site is the very ancient city, where the Trojan War took place, against Mycenaean Greece.
The city remains on the northwest coast of Turkey and has started a debate of thousands of years of mythology and history, with some believing that it is the very city of Troy, and some not.

#3 King Tut’s Tomb

As another archaeological find that has been featured in films and many books, King Tut’s Tomb included a lot of mystery. King Tut (Tutankhamun), was the Egyptian pharaoh. His tomb was discovered in 1922, by archaeologists.
The pharaoh received his title in 1332 B.C, when he was just 9-years old, and died at the age of 18. His death was discovered to be sudden, and the build of the tomb rushed, which was quite strange, given that Egyptians spend a lot of time perfecting everything they made.
The burial chamber is still praised by archaeologists until today, considering that it is covered in treasures and golden artefacts. There is still a myth till today, that the tomb is cursed and that whoever discovers it, will suffer under the curse.

#4 Dead Sea Scrolls

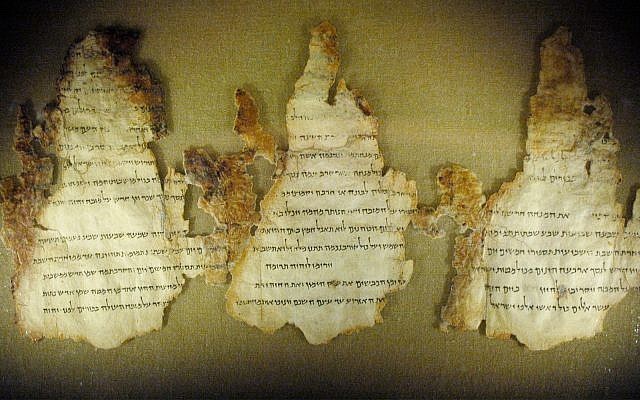
Dead Sea Scrolls

The Dead Sea Scrolls were discovered in the 1940’s near the ancient site of Khirbet Qumran, by a young man.
Archaeologists believe these scrolls to date back 250 B.C. and A.D. 68. These scrolls, fascinated archaeologists, due to it dating back to so long ago. After it was discovered, researchers also discovered over 900 manuscripts in caves, in the surrounding area of the ancient site, which was all copies of Exodus, Genesis, Isaiah, Kings, as well as Deuteronomy, from the Bible. These scripts are said to be the earliest copies of the Hebrew Bible, which are now kept safe in Jerusalem.

Read More

Geelong’s Nyaal Banyul records 12,200 attendees as local suppliers join the event business

November 16, 2026November 6, 2026

Geelong’s new convention centre welcomed more than 12,200 attendees across 15 events in its first month after opening in July. Nyaal Banyul’s August update recorded conferences and gala functions alongside a community open day and careers expo.

The first visitors were using a precinct that already had local businesses supplying it. At opening, project partner Plenary said more than 50 local firms were involved in event delivery and the supply of food, wine and equipment.

A subsequent Victorian Government release estimated that the first month’s events injected around $1.2 million into the local economy. It didn’t publish a breakdown showing which businesses received that spending.

Local gatherings and national conferences fill the same building

The early programme included the Associations Forum National Conference, Business Managers Victoria’s leadership conference and the Barwon Health Foundation Gala Ball. The Geelong Careers Expo and community open day brought another audience through the doors.

These aren’t all overnight visitors. Local residents are included in the attendance total, so it can’t be read as 12,200 additional tourists needing hotel rooms. Nor does attendance establish how much each person spent outside the venue.

General manager Rick Aylett described a programme alternating between large local gatherings and national conferences. Tourism Greater Geelong and the Bellarine executive director Tracy Carter reported that conference delegates had used hotels across the city, visited hospitality and cultural precincts and travelled further afield around their events.

A local evening function can bring demand for transport home or dinner afterwards. An interstate delegate may need additional nights of accommodation or somewhere to meet colleagues. What remains outside the venue’s arrangements depends on the programme and what the ticket already includes.

The government’s spending estimate cannot settle that question for an individual operator. Without the breakdown, dividing $1.2 million by total attendance would produce an average with no clear account of who bought what. A hotel and a supplier might both benefit through transactions made by entirely different customers.

The event mix also affects staffing. Several local evening functions could put pressure on a restaurant at different times from a multiday conference. A supplier making advance deliveries faces deadlines that don’t appear in the public session timetable.

The centre buys locally before delegates reach the waterfront

The $449 million development includes a 1,000-seat theatre, exhibition space and meeting rooms. Regional Development Victoria reported more than 80 events booked when construction completion was announced in June, ahead of the first event on 3 July.

Plenary identified more than 240 ongoing jobs at the centre and a 200-room Crowne Plaza hotel next door. The precinct is already equipped to serve some of the demand it brings; a visitor doesn’t arrive with every meal and room still to be booked.

But the centre also buys locally. The supplier relationships reported at opening include businesses whose work takes place before attendees arrive or behind the scenes during an event. They don’t depend on a delegate walking past their premises.

A firm offering equipment, food or event services may need to reach an organiser while plans are still being costed. Its ability to meet delivery windows and handle the required volume can matter more than being the nearest supplier.

That makes a different marketing brief from attracting visitors on the day. A supplier’s website may need to explain capacity and experience with comparable work. A restaurant’s page needs to make its availability and group-booking arrangements clear to someone with a short break between sessions.

A business can pursue both audiences, but the booking lead times will differ. Waiting until a conference begins could be too late for a supplier, while advertising a meal months beforehand may be premature for a delegate who hasn’t yet arranged their stay.

The precinct’s own catering and accommodation narrow some openings and leave others. Additional nights, informal meetings and independent group meals are possible sources of business. Their size has to be established through enquiries and bookings, rather than assumed from the theatre’s capacity.

The visitor figures provide a baseline for later results

The City of Greater Geelong reports 6.225 million visitors to the city-region in 2024, up 0.4% on the previous year. Domestic day trips declined 5.1%, according to the indicator, which draws on Tourism Greater Geelong and the Bellarine data.

“Geelong, the Surf Coast and the Bellarine are different markets,” says Scalepoint in Geelong on its website. Conference delegates face a smaller catchment again when they have only a gap between sessions to find a meal or attend a meeting. A business elsewhere in the region isn’t necessarily within that visitor’s practical reach.

Those regional visitor figures use a different measure from the convention centre’s attendance count. They include a much wider period and territory; the event count includes locals. Adding the two would overstate what the available numbers establish.

The centre may change the timing of visits as well as their purpose. A conference attendee follows an organised programme, potentially with time before or after it to spend elsewhere. The first month alone is too short to establish a lasting change in hotel occupancy or seasonal demand.

Local businesses can nevertheless record the work they receive now. An event name on a group booking, an organiser’s delivery request or a customer’s explanation of how they found the business provides a link that an attendance total cannot.

Those records can also expose limits. Additional staff or extended hours may absorb much of a booking’s revenue. Promotion tied to the next event needs to account for those costs and the tables, rooms or delivery slots still available.

Plenary’s opening announcement also named the precinct’s public space: Gheringhap Plaza. Beyond the theatre and meeting rooms, that is another physical location businesses can use when giving unfamiliar visitors directions around the waterfront.

Read More

Australia Post’s 2026 report shows online spend hit $82.6 billion, and boxes are getting smaller

September 19, 2026August 18, 2026

Australians spent $82.6 billion online in 2025, a 14% jump year on year, according to Australia Post’s latest eCommerce Report. Close to 9.8 million households now shop online, and the average shopper is buying from 16 different brands a year and making four more individual purchases than the year before.

The twist in the data is that average basket size has actually fallen to $96, meaning more parcels are moving through the system carrying less in each one. That has direct consequences for anyone shipping physical product, because more, smaller shipments means more individual boxes doing the branding work a single larger order used to do.

Smaller baskets mean more first impressions, not fewer

When a customer bought less often but in bulk, packaging was a once-a-quarter touchpoint. With four extra purchases per household per year and shrinking basket sizes, the box arriving on the doorstep is becoming a far more frequent brand interaction than it used to be for most retailers.

Businesses shipping direct to consumers are recognising that a plain shipping box no longer cuts it when the unboxing moment happens this often. Sellers using Star Stuff Group cartons Australia-wide are betting that the extra print cost pays for itself across a customer base now opening a branded parcel several more times a year than the report showed two years earlier.

That bet only pays off if the box itself is built to survive courier handling as well as it looks on a shelf. A carton that photographs well but crushes in transit undoes the branding effort before the customer even opens it.

The rise of marketplaces adds another packaging pressure point

Pure online marketplaces accounted for $18.9 billion of the total spend, close to a quarter of all online expenditure. Selling through a marketplace rather than a direct storefront makes it harder for a brand to control the customer experience at every stage, which puts more weight on the one part a seller still controls completely: the box itself.

A generic carton arriving from a marketplace order tells the customer nothing about who they bought from. A printed one does the job a storefront normally would, at the exact moment the customer is forming their first impression of the seller.

That’s a harder problem for sellers who split volume across several marketplaces at once, since the packaging itself has to carry brand recognition consistently across every channel a customer might have ordered from, not just the one with the nicest storefront design.

Recommerce growth adds a second life to every carton

Nearly half of Australians now buy second-hand goods annually, and 73% say they’re interested in buying pre-loved or refurbished items directly from retailers, even though only 14% of businesses currently offer that option. As resale programs catch up to that demand, packaging built to survive a second shipping trip becomes more relevant than packaging designed for a single one-way delivery.

The report’s numbers point to a market where parcels move more often, in smaller batches, through more channels, and where the box itself carries more of the brand’s weight with every trip it makes.

Six in ten Australians are now using AI tools while shopping, the report also found, with younger buyers leaning on agent-led purchasing at a much higher rate than older demographics. As more of the buying decision gets automated or delegated to an assistant, the physical arrival of the parcel becomes one of the few remaining moments where a brand can still speak directly to the person who bought it.

That reality is pushing packaging further up the priority list for retailers rethinking their online strategy for the year ahead, rather than treating it as a line item to be minimised once the sale itself is locked in.

Read More

How Manufacturer Certification Fits Austin’s Post-Hail Roofing Backlog

September 3, 2026

Central Texas is accustomed to hail-driven repair surges, and statewide claim data shows why contractor availability can tighten quickly after a major storm. When many households begin inspections and claims at once, scheduling becomes a regional capacity problem rather than a single-contractor problem.

That search is harder than it sounds. Texas hasn’t had one bad hail year. It’s had over a decade of them.

The National Insurance Crime Bureau recorded roughly 902 major hail events with significant damage in Texas in 2025, more than double the total logged by Illinois, the next-highest state. State Farm, the largest home insurer in Texas, processed 95,200 hail claims that year, with an average payout near $15,000 per claim. That volume, compounding year after year, is a large part of why Austin homeowners now wait weeks rather than days for a qualified crew.

Material availability can become a second bottleneck after a widespread storm. Even when a crew has an opening, a job may still wait on a specific shingle line, color, underlayment, flashing component, or other material needed to match the approved scope.

That secondary bottleneck compounds the labor shortage instead of replacing it. A contractor with an open crew slot can still be stalled if the shingle color or product line a homeowner’s insurance claim specifies is temporarily out of stock.

Why Manufacturer Certification Can Narrow the Available Contractor Pool

Not every roofing contractor carries manufacturer certification, and that distinction matters more after a hail season than most homeowners realize. Certified installers complete product-specific training, follow documented installation standards, and are eligible to offer extended warranty coverage that non-certified crews can’t provide.

Certification matters most when a homeowner wants access to manufacturer-backed warranty options that depend on an approved installer. That does not mean an insurer or lender universally requires a certified contractor; it means certification can affect which warranty packages are available after the work is complete.

That distinction can narrow the practical contractor pool for homeowners who want a particular manufacturer’s enhanced warranty. The fastest available crew and a manufacturer-certified installer are not always the same contractor. For homeowners dealing with that post-storm bottleneck, an established roofing contractor in Austin is still worth checking for manufacturer credentials and warranty eligibility before signing.

Certification also does not guarantee immediate availability. A manufacturer network can help homeowners identify contractors who meet that program’s requirements, but those contractors still face the same labor, weather, and material constraints as the rest of the market.

Homeowners rarely hear this explained up front, which is part of why so many are surprised at how long a seemingly simple repair takes to schedule after a major hailstorm.

The Claims Math That Is Driving Homeowner Behavior This Year

Average payouts near $15,000 sound generous until they’re measured against 2026 material and labor costs, which have climbed steadily due to tariff pressure on steel, aluminum, and imported components. Many homeowners are discovering a full tear-off and replacement now costs more than their claim check covers.

When replacement costs are high, homeowners have more reason to compare warranty terms, contractor credentials, and the written scope of work rather than accepting the first available bid.

If damaged shingles, flashing, or decking remain exposed to additional rain, a limited repair can grow into a larger water-intrusion problem. That risk is enough to make temporary protection and timely repair important.

A delay can also make the damage history harder to untangle. The longer a roof remains exposed to additional weather, the harder it may be to separate the original storm damage from problems that developed afterward.

That makes documentation important. Dated photos, inspection reports, estimates, and repair records create a clearer timeline if the scope of work changes later.

Homeowners do not need a complicated system: a folder with dated photographs, the claim paperwork, and contractor inspection notes is usually more useful than trying to reconstruct the sequence months later.

What the Repair Backlog Signals About Austin’s Broader Housing Stock

Austin’s rapid growth over the past decade means a large share of the metro’s housing stock was built or re-roofed within a similar window, using similar shingle products from a handful of major manufacturers. That clustering means storm damage tends to hit entire neighborhoods with roofs of comparable age at roughly the same time.

When one storm system damages thousands of roofs installed in the same five-year period, the repair timeline stops being about any single contractor’s capacity. It becomes a regional supply-and-demand problem across the entire certified installer network.

Texas has topped national hail-damage rankings consistently enough that this pattern will likely persist through the rest of 2026’s storm season and into next year’s. For homeowners, that means treating roof inspections and contractor vetting as an early-season task, not something to handle only after damage appears.

That makes contractor vetting especially important after a storm surge. Homeowners comparing bids can check manufacturer credentials, insurance, local business history, and warranty eligibility before signing.

The larger point is that hail-related backlogs can recur whenever demand spikes across the region. A contractor directory or certification network is useful because it gives homeowners another screening tool; it does not remove the underlying capacity constraint.

The fastest available contractor and the most qualified one aren’t always the same option this year. The backlog itself is evidence that a lot of households are learning that distinction the hard way.

Read More

What the 50% Aluminum Tariff Means for Las Vegas Patio Covers Built in the USA

August 10, 2026August 4, 2026

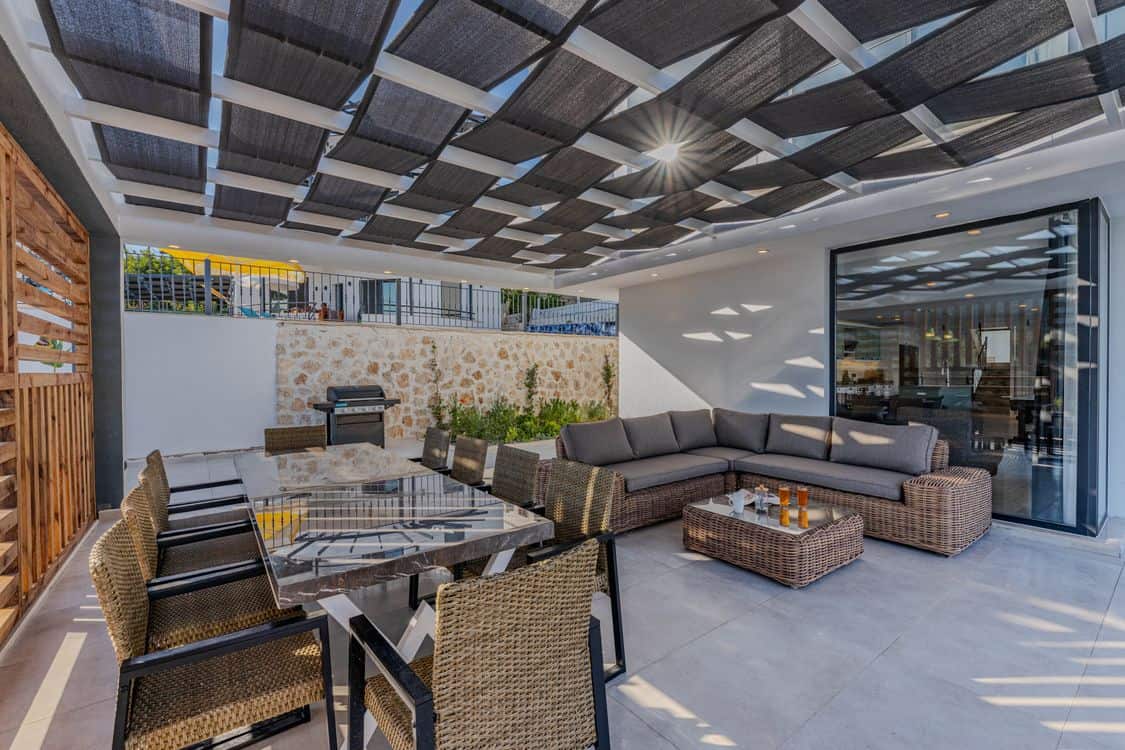
Aluminum doesn’t usually make the local news in Las Vegas. It’s the metal holding up half the patios in the valley, and nobody thinks about where it comes from until the price moves. In 2025 the price moved hard.

That June, the federal government doubled Section 232 tariffs on imported steel and aluminum from 25% to 50%, and it took effect within hours of the announcement. For an industry that runs on aluminum extrusions, that’s not a footnote. It reprices the whole job.

For anyone weighing a patio cover, the ripple is worth understanding, because it quietly reshapes which products make sense and which companies can still stand behind their quotes.

Why a trade policy shows up on your patio quote

A patio cover is, structurally, a lot of aluminum. Posts, beams, roofing panels, fasteners. When the metal underneath all of it gets more expensive, so does the finished product, and the increase doesn’t land evenly across the market.

Companies leaning on imported extrusions felt it right away. Suppliers reported softer order volumes as the higher tariff worked through the extrusion market and pushed domestic aluminum premiums up. Every link in that chain eventually reaches the customer.

The wrinkle for Las Vegas is that the two big patio-cover product lines here, Alumawood and Elitewood, are made domestically. That was already a selling point for quality and warranty reasons. It’s become a price-stability point too.

Made in the USA stopped being just a slogan

For years, “made in America” on a patio-cover brochure read like patriotic filler. In this trade climate it carries real money behind it.

Domestically produced aluminum systems sit behind the sharpest edges of import tariffs on finished goods. That doesn’t make them bulletproof. Raw aluminum prices move worldwide, and tariffs push domestic premiums up right along with them. But a product smelted, cast, and built inside the country skips the layered duties stacking onto imported derivatives.

The practical effect: a homeowner comparing quotes may find domestic aluminum systems holding their pricing steadier than products tied to a jumpy import pipeline. Steady pricing is worth something when you’re financing the work.

What this means if you’re deciding now

None of this is an argument for panic buying. It’s an argument for asking where the metal comes from.

Ask where the aluminum in a proposed system originates. Ask whether the warranty survives the company’s own supply headaches. In a market where material costs are being reshaped by policy, the origin of the metal isn’t a trivia question anymore.

The valley’s appetite for shade isn’t going anywhere. Las Vegas needs patio covers the way colder cities need furnaces. What the tariff era changes is the calculus of how those covers get built, and by whom, and at what price they hold.

Underneath the finish, a patio cover is a commodity product exposed to global forces. The buyers who come out ahead are the ones who treat it that way.

Read More

What the Harvard Dental Desert Study Says About Reaching a Specialist in a Town Like Kyle

July 19, 2026July 5, 2026

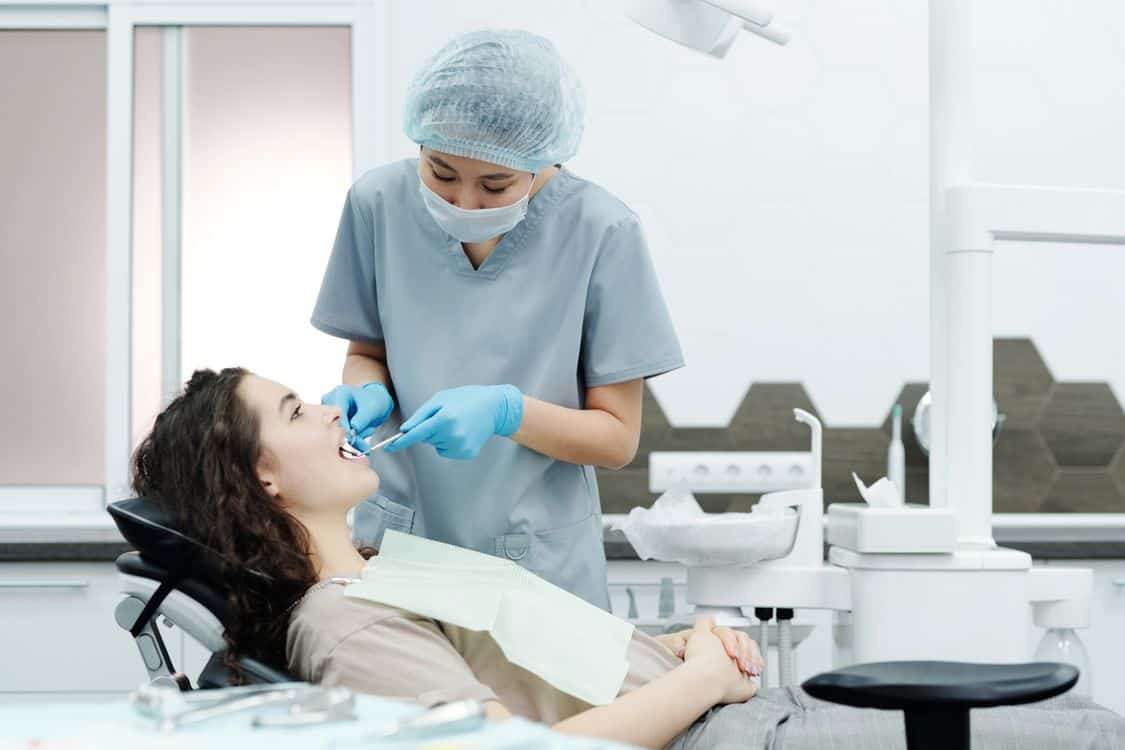
Most conversations about access to dental care focus on insurance and cost. A study out of Harvard reframed the problem in terms of distance and distribution, and the picture it produced is uncomfortable for anyone who assumed a dentist is always nearby.

The researchers mapped where dental clinics actually sit relative to where people live, down to the smallest census units. What they found was less a shortage of dentists overall than a lopsided scattering of them.

That distinction carries real weight for fast-growing suburban and exurban communities, where the gap between general care and specialized surgical care is often widest.

The Geography of Who Can Reach Care

The Harvard team, publishing in early 2025, found that nearly 24.7 million Americans live in areas classified as dental care shortage zones. Some 1.7 million lack a clinic within a 30-minute drive at all.

What set the study apart was its resolution. Rather than relying only on broad shortage-area designations, the researchers used a gravity-based method that weighed clinician supply against population demand at the level of individual census block groups. It caught gaps that coarser maps had missed.

The disparity sharpens in rural areas, where the ratio runs to roughly one dentist for every 3,850 residents, compared with one for every 1,470 in urban areas. The team called these underserved pockets dental deserts.

A follow-up line of research from the same group added a detail that matters here. Specialists, as opposed to general dentists, were substantially less likely to practice in shortage areas. Advanced care concentrates where the population and economics support it.

That is the structural reality behind a frustration many patients feel without naming it: finding a general dentist is one thing, and finding someone who does complex surgical implant work is another entirely.

“For complex cases, the real question patients face isn’t whether there’s a dentist nearby. It’s whether there’s one who does this specific work without an hour’s drive,” notes Dr. Kimmel of Fixed Dental.

The state-by-state breakdown drives the point home. Alaska led the country with more than 10 percent of its population living in a dental desert, followed by Montana and North Dakota. Only a handful of states and the District of Columbia had no dental deserts at all.

The burden also tracks with disadvantage. Counties with care shortages had higher shares of residents below the poverty line and higher rates of being uninsured, and the researchers noted the picture is likely worse still for people on Medicaid or Medicare, who face additional barriers because fewer dentists accept them.

Why a Booming Suburb Sits in an Awkward Middle

A place like Kyle is not a rural dental desert in the Alaska-or-Montana sense the study highlights. It is something more ambiguous, and arguably more overlooked.

Population is arriving faster than specialty infrastructure can form. The town has general dentistry. What it has historically lacked, like many exurban communities, is a deep bench of clinicians focused specifically on implants, full-arch reconstruction, and sedation.

When a specialty is thin on the ground, patients do one of two things. They drive to a metro center, often Austin or San Antonio, or they wait until a problem becomes urgent. Neither is good for outcomes.

A local practice that has committed to implant work changes that equation for its catchment area. It pulls advanced care out of the distant metro and into the corridor of smaller towns that would otherwise feed their hardest cases elsewhere.

Follow-up research on the dental workforce sharpens why that is unusual. Early-career dentists were found to be more likely to work in underserved communities, but that likelihood faded as careers progressed, and specialists in particular gravitated toward better-resourced areas. The natural drift of the profession runs away from places like this, not toward them.

What the Map Should Tell Patients

The lesson of the dental desert research is not to panic. It is to recognize that proximity to advanced care is a real variable, not a given, and to factor it into decisions.

For routine work, almost everyone in a growing Texas suburb is fine. For the harder categories, the ones involving surgery, anesthesia, and on-site fabrication, the supply is genuinely uneven, and it thins out fast once you leave the larger cities.

The cost of that thinness is delay. When advanced care is far away, people defer it, and dental problems do not improve with waiting. A small issue caught early is cheaper, simpler, and less painful than the same issue met after months of putting it off because the nearest capable provider felt out of reach.

This is also a reason the established local specialist matters more than its quiet profile suggests. In a discipline that the data shows clusters away from underserved areas, a practice that anchors that capability in a smaller market is doing something the national distribution pattern does not naturally produce.

That is not a marketing claim so much as a reading of the map. The default gravity of the profession pulls advanced care toward dense, affluent metros. Where a specialty practice bucks that pull and plants itself in a fast-growing exurban county, it is filling a gap the broader system tends to leave open.

The Harvard work measured deserts in miles and drive times. The takeaway for an individual patient is narrower and more personal. Know where the nearest provider for your specific need actually is before you need them urgently, because for the advanced procedures, the answer is rarely as close as you would assume.

It is a small piece of homework that pays off precisely when stress is highest. The worst moment to discover that the nearest implant specialist is an hour away is the moment a tooth has already failed and the clock is running.

Read More

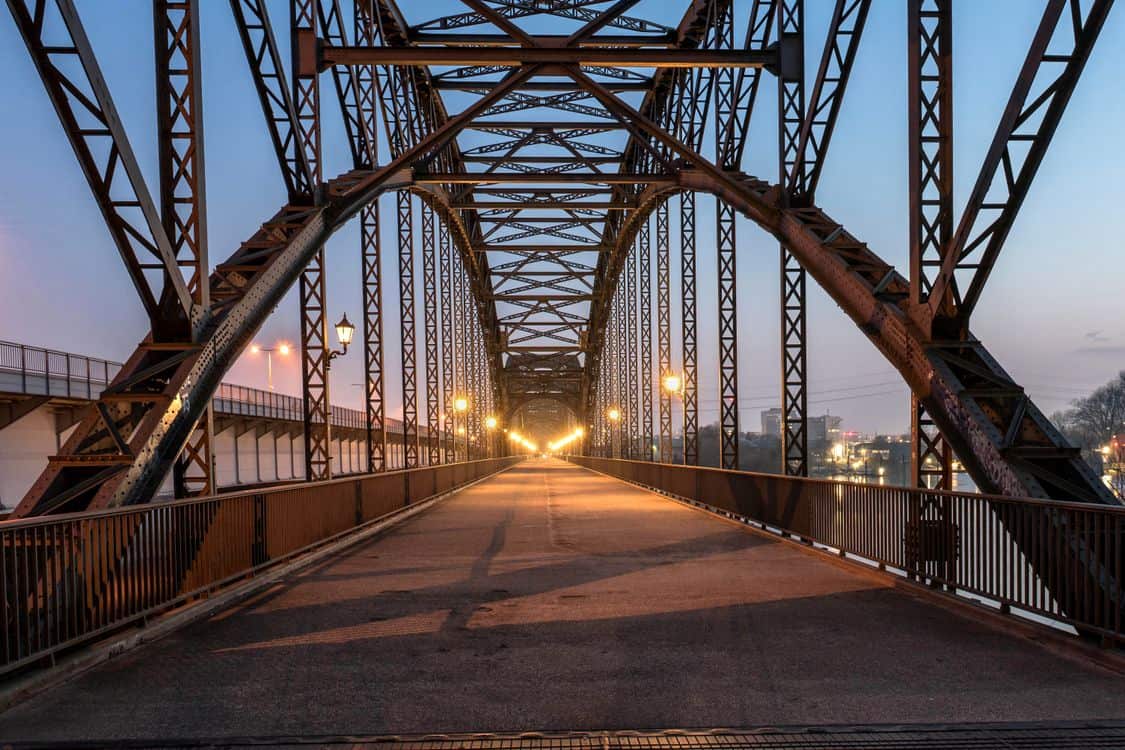
What the Fern Hollow Collapse Taught Bridge Engineers About Weathering Steel

July 9, 2026June 14, 2026

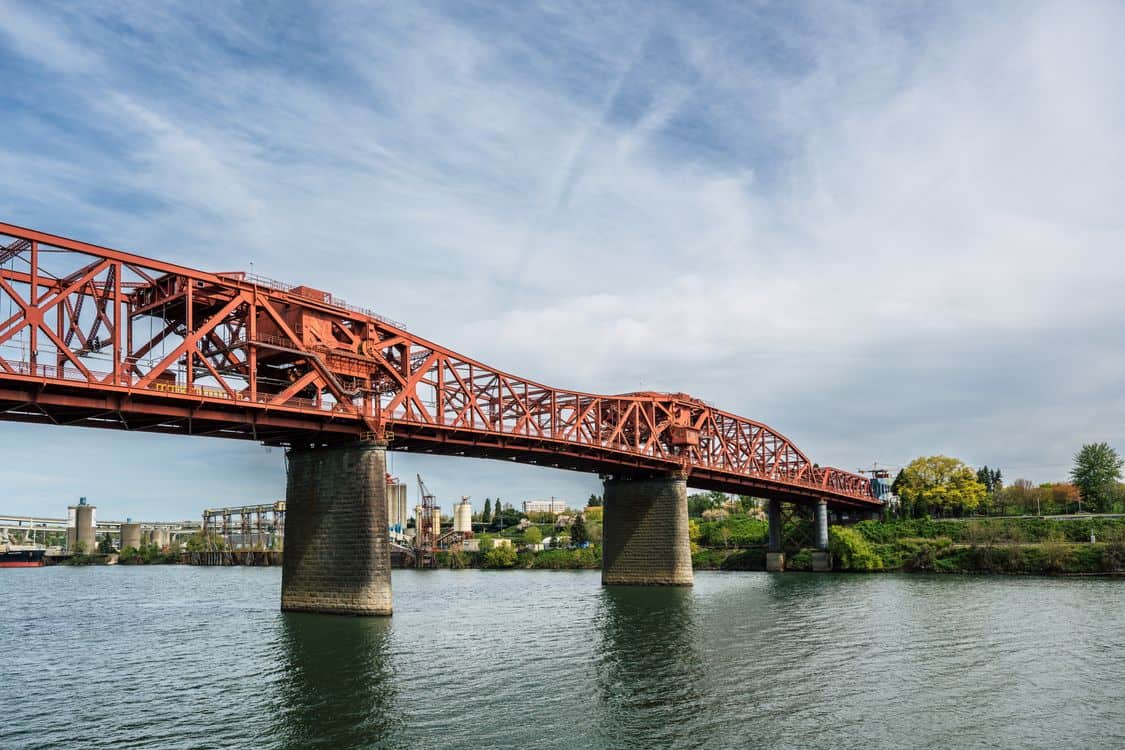
On a January morning in 2022, a bridge in Pittsburgh simply gave way. The Fern Hollow Bridge dropped into the park below, and the investigation that followed put a renewed spotlight on a material that has carried American highways for half a century.

The lesson that emerged was not that weathering steel is a bad bridge material. It was something more nuanced, and more important, about how the material has to be cared for.

A collapse that focused the industry’s attention

The failure was dramatic. According to the National Transportation Safety Board, the bridge fell approximately 100 feet into the park below, with vehicles on or near it at the time.

Investigators found severe corrosion and section loss on all four of the bridge’s legs. In places, the loss was so advanced that it had eaten holes clean through the steel.

The cause traced back to water. Debris and leaves had blocked the drainage, allowing water to pool against the steel in areas never meant to stay wet.

That standing water prevented the protective patina from forming and instead drove relentless corrosion. The very mechanism that makes weathering steel durable had been undermined by poor drainage and incomplete maintenance.

Why weathering steel still belongs on bridges

It would be easy to read that as an indictment of the material. The engineering community read it differently, and correctly.

Weathering steel earns its place on bridges because, detailed properly, it eliminates the need for paint. That removes the single largest long-term maintenance cost of a steel bridge, the endless cycle of blasting and repainting.

A structural weathering grade like ASTM A588 is specified across highway bridges precisely for that reason, offering the strength of a structural steel with a self-protecting surface that resists corrosion when it can dry out.

The key phrase is “when it can dry out.” The patina is a deal the material makes with its environment, and the environment has to hold up its end.

That means designing the bridge so water runs off and away, keeping drainage clear, and inspecting the details where debris collects. Get those right and uncoated weathering steel can outlast painted alternatives with a fraction of the upkeep.

The post-collapse guidance from federal authorities reinforced exactly this. The focus was on inspection, drainage, and follow-up maintenance, not on abandoning the material.

What it means for specifiers and suppliers

For bridge owners and the engineers who serve them, Fern Hollow is a reminder that material choice and maintenance are inseparable.

Specifying weathering steel is not a license to forget about the structure. It is a commitment to detailing and upkeep that lets the material’s self-protecting nature actually work.

With a large share of American bridges aging and a steady pipeline of replacement and rehabilitation work, the structural weathering grades remain a core part of the bridge engineer’s toolkit.

For suppliers, that means demand is durable, but it comes with a responsibility to support correct use, from grade selection to an understanding of where weathering steel thrives and where it does not.

The Fern Hollow collapse was a tragedy that prompted hard questions. The answer was not to walk away from weathering steel, but to respect the conditions it needs. Detailed and drained correctly, it remains one of the most cost-effective ways to build a bridge that lasts.

Read More

The Automation Anxiety Index: Which Professions Are Panicking About AI

May 31, 2026May 23, 2026

Financial advisors have seen search interest in AI alternatives surge by 166% since January 2025, with job security queries spiking 200% over the same period. That’s not theoretical anxiety – it’s professionals actively researching whether machines will take their jobs, and the data suggests they have reason to worry.

As ChatGPT ranks seventh in global searches and “AI” itself hits 13th most-searched worldwide, certain professions are experiencing existential dread while others remain surprisingly unconcerned about being replaced by AI.

Finance Leads the Panic

The financial sector dominates both metrics: highest increase in searches for AI alternatives and highest surge in job security concerns. Accountants follow financial advisors closely, with “AI accountant” searches doubling since the beginning of the year and “will AI replace accountants” queries up 60%.

The pattern makes sense when you consider what financial advisors and accountants actually do. Much of the work involves processing numerical data, identifying patterns, generating reports, and making recommendations based on rule-based analysis – precisely the tasks that current AI excels at. Robo-advisors have been nibbling at the edges of wealth management for years. AI-powered tax software has been automating basic accounting functions for just as long.

What’s changed is capability and accessibility. Tools that once required specialized knowledge to deploy are now consumer-facing. Someone with moderate financial literacy can ask ChatGPT to analyze their portfolio allocation or review their tax strategy and get surprisingly coherent guidance. They might not follow it without professional verification, but the fact that the AI can generate plausible analysis at all shifts the value proposition.

The Coder Paradox

Coders rank third for increase in AI alternative searches, up 88% – but here’s where it gets interesting. Unlike finance professionals, coders’ job security concerns have remained stable or even decreased. The people building AI systems seem less worried about AI replacing them than the people working in industries AI might disrupt.

This paradox might reflect insider knowledge. Programmers working with AI tools daily understand their limitations more clearly than outsiders. They see the hallucinations, the logical errors, the inability to handle complex system architecture. Yes, GitHub Copilot can autocomplete code snippets. No, it can’t architect a distributed system or debug production issues at 3 AM.

Scientists (+35% in AI alternative searches) and data analysts (+50%) show similar patterns: modest increases in tool interest but minimal job security anxiety. These technical fields seem to view AI as augmentation rather than replacement, possibly because practitioners understand the gap between narrow task automation and full role displacement.

The Creative Crash

Artists present the opposite trajectory. “AI art” searches have plummeted 19%, dropping from 271,000 monthly to 220,000 despite remaining the most-searched AI profession alternative in the dataset. The initial fascination with AI-generated imagery is giving way to reality: the novelty has worn off, the limitations have become clear, and the ethical concerns around training data theft have soured enthusiasm.

This decline suggests a market correction. When AI art tools first exploded in popularity, they generated hype that outpaced utility. Millions experimented with generating images, discovered the outputs were interesting but rarely usable for professional purposes, and moved on. What remains is a smaller base of actual users rather than curiosity-driven experimenters.

Therapists show a similar if less dramatic decline. Despite steady concern about job replacement, searches for “AI therapist” dropped 13%, from 15,000 monthly to 13,000. The profession still ranks fifth highest for AI alternative search volume, but the trajectory points to growing skepticism about whether AI can genuinely replicate therapeutic relationships.

The Tech Industry’s Strange Retreat

The most striking data comes from the technology sector itself. Programmers saw AI alternative searches drop 28.57%. Software engineers dropped 56.45%. Marketing assistants crashed 68% – the steepest decline in the entire dataset, tumbling from 89,000 monthly searches in January to just 28,000.

For software engineers, this creates a paradox: search interest in AI tools cratered by more than half, yet anxiety about job replacement jumped 44%. The divergence suggests two possibilities. First, engineers tested AI coding assistants, found them wanting, and stopped searching – but remain worried about future improvements. Second, the job market contracted enough to create displacement anxiety independent of AI’s actual capabilities.

The marketing assistant decline probably reflects hands-on disappointment. The promise of AI-written copy that matches human creativity hasn’t materialized. Most professionals who tested these tools discovered they produce generic, soulless content that requires extensive editing to be usable. After that firsthand experience, interest evaporated.

Doctors vs. Therapists: The Trust Divide

Searches for “AI doctor” rose 25%, while “AI therapist” dropped 13%. People apparently trust AI more with physical diagnosis than emotional support – a revealing split about where we think machines add value versus where human connection matters.

The medical uptick makes logical sense. AI diagnostic tools can process more data, identify more patterns, and access more research than any individual physician. IBM’s Watson for Oncology and similar systems have demonstrated genuine diagnostic utility. A 25% increase in search interest suggests growing public awareness and acceptance of AI in clinical settings.

The therapy decline reflects the opposite realization. Mental health treatment depends fundamentally on relationship, trust, and human empathy. An AI can pattern-match symptoms to treatment protocols, but it can’t provide the emotional attunement that makes therapy effective. Recent research highlighting risks of AI therapy – including inappropriate responses and inability to handle crisis situations – has likely dampened enthusiasm.

What the Search Data Actually Means

These search patterns don’t perfectly predict job displacement – they measure anxiety and curiosity more than actual replacement risk. But they reveal how different professions perceive AI threats, and those perceptions shape behavior.

Financial professionals actively researching AI alternatives and job security are likely considering career pivots, skill development, or ways to differentiate themselves from automation. That preemptive adaptation might protect them even if AI capabilities expand. Artists who’ve given up searching for AI art might be doubling down on uniquely human creative processes that machines can’t replicate.

The tech sector’s declining interest despite rising anxiety suggests something darker: resignation. Engineers know AI coding tools aren’t good enough to replace them yet, so they’ve stopped actively researching alternatives – but market conditions have created displacement pressure anyway, making them worry despite the technology’s limitations.

The Skills That Survive

Across professions, certain patterns emerge. Jobs heavy on data processing, pattern recognition, and rule-based decision-making face the highest AI interest and anxiety. Jobs requiring complex human interaction, creative problem-solving, or physical presence show lower concern and declining search interest.

Financial advisors process data and make recommendations – automatable. Therapists build relationships and provide emotional support – not automatable with current technology. Accountants follow tax codes and generate reports – automatable. Artists create original expressions and make aesthetic judgments – partially automatable for technical execution but not for conceptual development.

The adaptability advice is consistent: specialize in niches, develop soft skills, and stay agile. A financial advisor who builds deep client relationships and handles complex estate planning is less replaceable than one who just rebalances portfolios. An accountant who provides strategic tax planning is more valuable than one who just files forms.

The 2026 Labor Market Reality

Search interest surging or plummeting doesn’t determine actual job losses – that depends on technology capability, economic conditions, regulatory environment, and social acceptance. But these search patterns reveal where workers see threats and opportunities, which influences training decisions, career changes, and salary negotiations.

If financial professionals believe AI will displace them, they’ll demand higher compensation for uncertainty or pivot to adjacent roles. If employers believe AI can substitute for entry-level analysts, they’ll reduce hiring and compress wages. These dynamics can create displacement even before technology is actually capable of full replacement.

The creative sector’s declining interest in AI tools might protect jobs by demonstrating limits. If clients consistently prefer human-created work after testing AI alternatives, that creates market resistance to automation regardless of technological capability. Marketing assistants who’ve proven AI can’t match their creativity have data to support their value propositions.

For workers in anxious professions, the message is clear: AI might not replace you, but your employer’s belief that it could will reshape your working conditions. The search data measuring that anxiety is trailing indicator of perceived risk and leading indicator of career decisions that will ripple through labor markets for years.

Read More

Tooth Decay Is Now NSW’s Top Cause of Preventable Hospital Stays, and the Bill Is Climbing

May 31, 2026

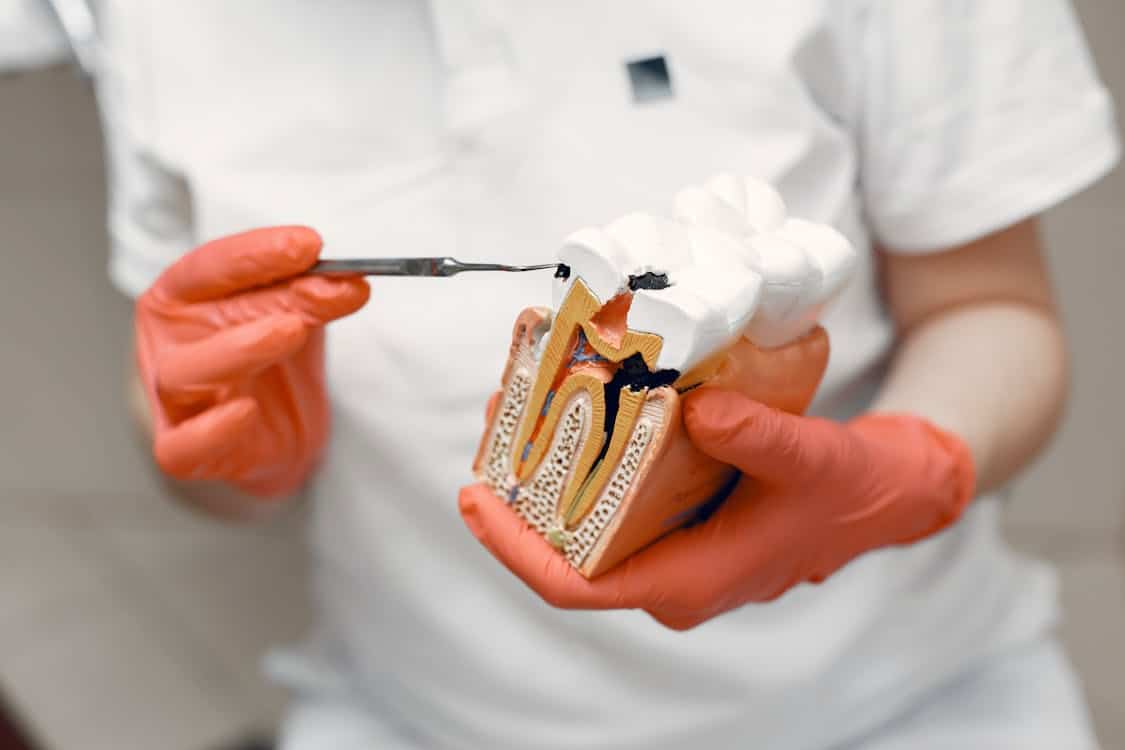
When people picture a hospital admission, dental problems are not usually what comes to mind. Yet across New South Wales, untreated teeth are sending people to hospital in numbers that have quietly made dental conditions the single largest cause of preventable admissions.

A recent analysis put a price on it, and the figure is hard to ignore.

What the NCOSS Report Found

The NSW Council of Social Service, working with Mandala Partners, examined the scale of dental-related hospitalisations across the state. Their October 2025 report found these admissions cost the NSW health system about $147 million a year.

There were roughly 24,300 such hospitalisations in 2022, and on current trends the annual cost is projected to climb toward $212 million by 2033, an increase of around 44 per cent. Dental conditions, the report concluded, are now the leading cause of potentially preventable hospitalisations in the state.

The overwhelming majority of these admissions trace back to one thing: complications from untreated tooth decay and cavities. Problems that started small, went unaddressed, and eventually became serious enough to require a hospital.

Children carry a striking share of the burden. The report estimated around $80 million in annual costs for children aged 0 to 14 alone, with tooth decay the leading reason young kids end up in hospital for dental reasons.

Why “Preventable” Is the Key Word

The label matters. These are not freak accidents or unavoidable disease. They are, by definition, hospitalisations that earlier and more accessible dental care could have headed off.
A cavity treated at a routine visit never becomes the abscess that lands someone in an emergency department. A child seen regularly is far less likely to need multiple teeth treated under general anaesthetic. The hospital admission sits at the end of a long road of missed opportunities for cheaper, simpler care.

That is the real argument for regular check-ups. They are not just about the individual tooth in front of the dentist; they are the mechanism that stops a minor issue from ever reaching the acute, expensive stage.
For families, the takeaway is practical rather than alarming. Establishing a relationship with a regular dentist and keeping up routine visits is the most reliable way to stay off the wrong end of these statistics. It is also why public health advocates keep urging people to choose your local dentist and attend consistently rather than only in a crisis.

What Actually Moves the Needle

The NCOSS report did not just diagnose the problem; it pointed to solutions, and they are revealing. Among the priorities were expanding dental programs in primary schools and remote communities, and lifting uptake of existing support like the Child Dental Benefits Schedule.

Notice the theme. Almost every recommendation is about getting people to a dentist earlier and more easily, because early access is what prevents the costly downstream admission.

For an individual, the lesson scales down neatly. The single most effective thing most people can do is remove the friction around routine care, making the regular check-up a normal habit rather than something that only happens when something hurts.

Tooth decay becoming a leading cause of hospital admissions is a striking failure of timing, not of medicine. The treatments are well understood and inexpensive when applied early. The cost only balloons when care is delayed until the problem can no longer be ignored.

Read More

The Tattoo Removal Market in Ontario Is Splitting Between Medical Clinics and Spas — With Very Different Results

May 27, 2026May 23, 2026

Walk into a medical spa in London, Ontario, and you’ll likely see laser tattoo removal advertised alongside facials and body wraps. Walk into a dermatology or plastic surgery practice, and you’ll see the same service, often using identical equipment, but with vastly different pricing, protocols, and outcome expectations. The growing divide between medical-grade tattoo removal and spa-setting treatments is creating confusion for consumers and raising questions about safety standards in an industry with minimal regulatory oversight.

The equipment at both types of facilities often comes from the same manufacturers — Q-switched and picosecond lasers that fragment ink particles so the body can eliminate them. But the similarity ends there. Medical clinics operate under physician supervision with protocols designed for complete ink clearance over multiple sessions, while spas frequently focus on fading tattoos enough to cover them with new work rather than pursuing full removal. Those different goals produce different treatment approaches and vastly different results.

Patient selection is another critical difference. Medical practitioners screen for contraindications — skin conditions, medications, immune disorders — that could complicate treatment or produce poor outcomes. Spa settings often operate with minimal medical oversight, performing treatments on clients who may not be suitable candidates. The consequences of that gap range from suboptimal results to actual complications like scarring, hyperpigmentation, or infections that require medical intervention.

For consumers seeking laser tattoo removal London Ontario, understanding this distinction is critical for making informed choices. The lower pricing at spas can look attractive, but incomplete removal that requires additional sessions at a medical facility to finish the job often costs more total than starting with medical-grade treatment from the beginning. The cheaper initial price becomes expensive when measured against final outcomes.

Training standards vary dramatically between settings as well. Medical laser operators in physician-supervised practices typically complete extensive certification programs covering skin anatomy, laser physics, safety protocols, and complication management. Spa technicians may receive minimal training — sometimes just manufacturer certification courses lasting days rather than weeks. That knowledge gap affects treatment quality, complication rates, and the ability to adjust parameters for different skin types and ink colors.

According to regulatory analysis from BC Medical Aesthetic, injectable treatments are restricted to licensed medical professionals in Canada, but laser procedures fall into a regulatory gray area where provincial oversight varies significantly. Ontario allows non-physicians to perform laser tattoo removal, which has enabled the spa market to flourish but also created safety concerns that medical organizations have flagged repeatedly.

The number of treatment sessions required illustrates the outcome difference starkly. Professional ink tattoos typically need 8-12 sessions for complete removal at medical facilities using optimal protocols. Spa settings often quote 4-6 sessions, which sounds better to consumers but rarely achieves comparable clearance. The gap between promised and actual results generates frustration and poor reviews that affect the industry’s overall reputation.

Pricing transparency is another area where medical and spa settings diverge. Medical clinics typically charge per pulse or per square centimeter, with costs clearly tied to the amount of work required. Spas often use package pricing that looks attractive initially but may not include enough sessions to achieve meaningful results, leading to upselling pressure for additional treatments that weren’t disclosed upfront. The lack of standardized pricing makes comparison shopping difficult for consumers.

Complication management represents perhaps the most significant difference between medical and spa settings. When side effects occur — blistering, infection, allergic reactions — medical clinics have physicians on-site or immediately available to address problems. Spas typically refer complications to external medical providers, creating delays and fragmented care that can worsen outcomes. For patients, that difference in backup support can matter enormously when things don’t go as planned.

The aesthetic medicine industry’s rapid growth in 2026 is bringing increased scrutiny to these quality gaps. Professional organizations are pushing for stronger licensing requirements and physician oversight mandates, but regulatory changes move slowly. In the meantime, consumers bear the burden of distinguishing between equivalent-looking services that deliver very different results. Education about these differences is improving, but it hasn’t reached most people who are just beginning to research tattoo removal options.

Looking ahead, the market is likely to continue fragmenting between medical-grade services and spa offerings unless regulatory changes force consolidation. For consumers, the practical takeaway is straightforward: laser tattoo removal is a medical procedure that benefits from medical expertise, regardless of where it’s being marketed. Choosing based on price alone without understanding the quality differences is a recipe for disappointment and potentially unsafe outcomes. The few hundred dollars saved at a spa rarely justifies the risks and inferior results compared to treatment at a physician-supervised facility.

Read More

What is Coding Automation and How Can It Help You? Explained

May 21, 2026April 25, 2026

Automation in coding is the practice of using scripts and tools to perform repetitive or rule based tasks that programmers used to do by hand. It reduces routine overhead so creative focus can shift to higher level problem solving and design.

People in small teams and large companies alike use it to speed up delivery cycles and reduce manual error. The idea is simple but powerful because small time savings add up fast.

What Is Coding Automation

Coding automation refers to software that runs tasks which follow clear patterns or rules without ongoing human input. Examples range from running tests and building releases to formatting code and generating boilerplate files.

The concept leans on patterns in language and behavior so the same sequence can be replayed reliably whenever needed. By treating code work as a set of repeatable moves one can chain tools to create reliable flows.

How Coding Automation Works

At its core there is a trigger a set of steps and an outcome where the trigger starts a program that executes scripted actions. Common triggers include changes in a repository scheduled timers or manual requests through a user interface.

Scripts and pipelines use small modules that perform single jobs then report results back to a log for review and recovery if something breaks. Many systems accept plugins that expand what a single step can do so pipelines remain flexible.

In modern development environments, AI-assisted programming now include platforms like Blitzy, which integrate into these workflows to streamline repetitive coding and review tasks. This kind of integration helps bridge scripted automation with intelligent assistance, making pipelines more adaptive without adding unnecessary complexity.

Tasks Well Suited For Automation

Routine activities that are rule based and predictable are ideal candidates for automation in code projects. Unit tests integration checks formatting refactor tasks and deployment sequences all fit this pattern because rules can be encoded clearly.

Data migration scripts repetitive scaffolding and repetitive configuration updates are also good fits since they often differ only in values. Anything that requires the same steps repeated many times with minimal judgment is worth automating.

Benefits For Individuals And Teams

Automating repeatable work saves time and cuts the number of small mistakes that creep in when tasks are done manually. Teams gain faster feedback loops so developers can find and fix faults earlier in the process rather than later when cost is higher.

It also frees people from drudge work which leaves room for creative problem solving and learning new techniques. When repetitive tasks are out of the way the team tends to move faster and feel less burned out.

Popular Tools And Platforms

There is a wide range of tools that support automation from simple script runners to full pipeline orchestrators that hook into source control. Continuous integration platforms can run tests on every change and report failures while command line tools can apply formatting or lint checks before code is submitted.

Many editors and integrated development environments support extensions that automate small tasks like completing boilerplate or refactoring names. Choosing tools often comes down to the balance between ease of setup and the level of control required.

Getting Started With Automation

Begin by listing tasks that take up time or cause frequent errors and pick one small item to automate so you learn the ropes without heavy commitment. Write a simple script or pipeline that runs the exact steps you take then test it carefully on sample inputs and edge cases.

Make logs concise and human friendly so anyone can scan results and act when a step fails rather than digging through a long dump. Train teammates on the new flow and iterate based on their feedback until the automation feels like a natural part of the work.

Common Pitfalls And How To Avoid Them

One trap is automating too much too quickly which can bury logic in opaque scripts that few understand or maintain. To prevent that write clear comments keep scripts modular and add simple tests for the automation itself so failures are easier to trace.

Another issue is rigid workflows that break when a project changes so prefer small modules that can be swapped instead of large monoliths that try to do everything. Finally plan for recovery steps so human intervention can happen safely when an automated run produces unexpected results.

Where Language Techniques Fit In

Simple linguistic tricks like stemming help search tools match code comments and commit messages even when developers use related forms of a word. Short n gram patterns detect common phrase sequences across logs and can highlight repeated error signatures that deserve a fix.

Frequency aware heuristics inspired by Zipf’s law can prioritize the most common errors for early automation which brings quick value. Applying these small language based ideas makes automation more resilient and easier to scale.

Scaling Automation Over Time

Start small then expand the scope as confidence grows and the code base stabilizes while keeping the change history clear and reviewable. Introduce automation in stages so the team can see benefits and suggest refinements that feel natural rather than forced.

Keep an inventory of automation tasks and retire ones that no longer fit current workflows to avoid brittle systems. A steady measured approach yields a system that supports work rather than getting in the way.

Read More
1 2 … 32 Next →
30 Great History Research Paper Topics
Categories Blog

30 Great History Research Paper Topics

9 Interesting Historical Events That Are Lesser-Known
Categories Blog

9 Interesting Historical Events That Are Lesser-Known

  • 7 years ago
Philosophy of History
Categories Blog

Philosophy of History

  • 7 years ago

Historical Events

Write Your Opinion

    Copyright @ 2020 ElgarHistory | All Rights Reserved. 2026.
    Powered by Eximious Magazine
    • Home
    • Blog
    • Archaeology
    • History Museums
    • Contact
    • Privacy Policy